Getting the keys to your new home is an exciting milestone. Whether it’s a BTO, resale HDB, or condo, the next big step is turning that empty space into a comfortable and functional home.
But renovation comes with a cost — and for many homeowners in Singapore, financing becomes an important consideration.
Two common options are renovation loans and personal loans. While both can help fund your renovation, they work very differently. Choosing the right one can impact your monthly cashflow, flexibility, and total repayment.
Understanding Renovation Loans
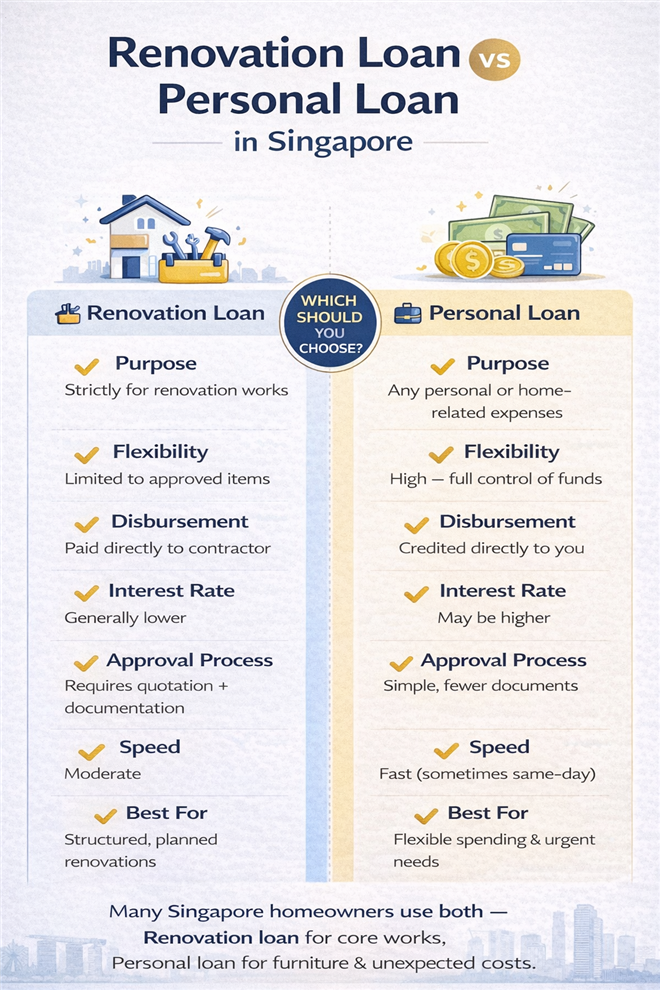
A renovation loan in Singapore is specifically designed to finance home renovation works. These loans are typically offered by banks and are meant for approved renovation purposes such as carpentry, flooring, electrical work, and painting.
However, renovation loans come with certain limitations.
They usually:
- Require a contractor quotation before approval
- Disburse funds directly to the contractor
- Cover only approved renovation items
- Have stricter eligibility criteria
This makes them suitable for structured, planned renovations — but less flexible for other expenses.
Understanding Personal Loans for Renovation
A personal loan offers more flexibility. Instead of being tied strictly to renovation works, the funds can be used at your discretion.
This means you can use a personal loan for:
- Furniture and appliances
- Interior décor
- Unexpected renovation costs
- Temporary housing during renovation
Unlike renovation loans, personal loans are usually disbursed directly to you, giving you full control over how the money is used.
Key Differences Between Renovation Loan vs Personal Loan
1. Purpose and Flexibility
Renovation loans are restricted to approved renovation works, while personal loans offer full flexibility for all home-related expenses.
2. Approval Process
Renovation loans often require contractor quotations and documentation, which can slow down approval. Personal loans generally have a faster and simpler process.
3. Disbursement
Renovation loans are typically paid directly to contractors. Personal loans are credited to your account, allowing you to manage payments yourself.
4. Loan Amount
Renovation loans may have limits based on renovation cost and property type. Personal loans depend more on your income and credit profile.
5. Speed
If time is a factor, personal loans are usually faster, making them suitable for urgent or ongoing renovation needs.
Which Option Is Better for Your Situation?
The better option depends on your renovation needs and financial situation.
Choose a Renovation Loan if:
- Your renovation scope is clearly defined
- You are working with a contractor
- You want a structured, purpose-specific loan
Choose a Personal Loan if:
- You need flexibility for multiple expenses
- You have additional costs beyond renovation
- You want faster access to funds
- Your renovation plans may change
The Reality: Many Homeowners Use Both
In practice, some homeowners in Singapore use a combination of both.
For example:
- A renovation loan for core renovation works
- A personal loan for furniture, appliances, and unexpected costs
This approach allows better control while maintaining flexibility.
Choosing the Right Financing Approach
Beyond choosing between renovation and personal loans, the key is ensuring that your repayment plan is sustainable.
Ask yourself:
- Can I comfortably afford the monthly repayment?
- Am I borrowing more than necessary?
- Do I have buffer savings after renovation?
Responsible borrowing ensures that your new home brings comfort — not financial stress.
Final Thoughts
Renovating your home is an exciting journey, but it also comes with important financial decisions. Understanding the differences between renovation loans and personal loans allows you to choose a solution that fits your lifestyle and needs.
For borrowers who require flexibility or faster access to funds, some choose regulated personal loan options from licensed moneylenders such as Sands Credit, where the focus is on clear terms and responsible lending.
Ultimately, the best choice is one that gives you both a beautiful home and peace of mind.
📌 FAQ (Q&A) — Renovation Loan vs Personal Loan in Singapore
Q: Can I take a renovation loan after my HDB reaches TOP?
A: Yes. Once your flat reaches TOP (Temporary Occupation Permit) or you receive the keys, you can apply for a renovation loan. Most lenders will require a contractor quotation and details of the renovation works before approval.
Q: What can a renovation loan be used for?
A: Renovation loans are typically restricted to structural and built-in works such as:
- Carpentry (wardrobes, cabinets)
- Flooring and tiling
- Electrical and plumbing works
- Painting and hacking
They usually cannot be used for furniture, décor, or appliances.
Q: Can I use a personal loan for renovation instead?
A: Yes. A personal loan can be used for renovation as well as related expenses like furniture, lighting, and appliances. It offers more flexibility compared to a renovation loan.
Q: Which loan is cheaper — renovation loan or personal loan?
A: Renovation loans generally have lower interest rates, but they are more restrictive. Personal loans may have slightly higher rates but offer greater flexibility and faster access to funds.
Q: How long does it take to get approved?
A:
- Renovation loan: May take longer due to documentation (contractor quotation, approvals)
- Personal loan: Usually faster, sometimes within the same day depending on the lender
Q: Can I take both a renovation loan and a personal loan?
A: Yes. Many homeowners in Singapore combine both:
- Renovation loan for core renovation works
- Personal loan for additional expenses like furniture and unexpected costs
Q: Will taking a loan affect my credit score?
A: Yes. Any loan will be recorded in your credit report. Making timely repayments can improve your credit profile, while missed payments can negatively impact it.
Q: How do I know which option is right for me?
A: It depends on your needs:
- Choose a renovation loan if you want lower rates and structured usage
- Choose a personal loan if you need flexibility and faster access
Q: Are licensed moneylenders a safe option for personal loans?
A: Yes, as long as they are registered with the Ministry of Law. Licensed moneylenders in Singapore operate under strict regulations, ensuring transparent terms and fair lending practices.