Borrowing money in Singapore is strictly regulated to protect consumers. While licensed moneylenders in Singapore operate under clear legal frameworks, unlicensed moneylenders — commonly known as “Ah Long” — continue to pose serious risks.
These illegal lenders often disguise themselves through modern channels such as SMS, WhatsApp, and social media, making it harder for borrowers to distinguish between legitimate and illegal offers.
Understanding the warning signs of an unlicensed moneylender is essential. Recognising these red flags early can help you avoid financial loss, harassment, and legal complications.
Why It Is Important to Avoid Unlicensed Moneylenders
Unlicensed moneylenders operate outside Singapore law. This means borrowers are not protected, and the lender is not bound by any regulations on interest rates, fees, or conduct.
Engaging with such lenders may lead to:
- Extremely high and hidden interest charges
- Aggressive or abusive debt collection
- Harassment of family members or colleagues
- Threats or intimidation
This is why choosing a licensed moneylender near you is always the safer and legal option.
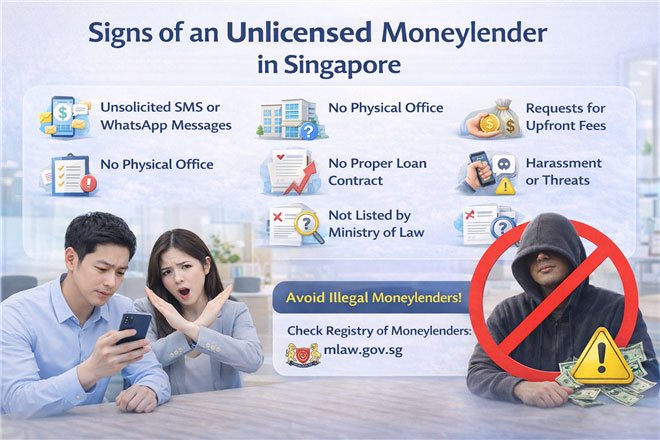
1. You Receive Unsolicited SMS or WhatsApp Messages
One of the most common signs of an unlicensed moneylender is receiving random loan offers via SMS or messaging apps.
These messages often include:
- “Fast cash guaranteed”
- “No documents needed”
- “100% approval”
Licensed moneylenders in Singapore are not allowed to advertise via SMS, WhatsApp, or cold calls. If you receive such messages, it is a strong indicator of illegal activity.
2. No Physical Office or Refusal to Meet in Person
A legitimate licensed moneylender in Singapore must operate from an approved physical office.
Unlicensed lenders often:
- Refuse face-to-face meetings
- Claim everything can be done online
- Avoid revealing their location
If you cannot verify a proper office address, it is best to walk away.
3. No Proper Loan Contract
Licensed moneylenders are required to provide a written loan agreement that clearly states:
- Interest rates
- Repayment schedule
- Fees and charges
Unlicensed lenders may:
- Skip contracts entirely
- Provide vague or incomplete terms
- Change conditions verbally
Never accept a loan without a clear, documented agreement.
4. Requests for Upfront Fees
Another major red flag is when a lender asks for processing fees before the loan is disbursed.
Licensed moneylenders in Singapore:
- Do not require upfront payments before approval
- Deduct fees from the loan amount only after approval
If you are asked to transfer money first, it is almost certainly a scam.
5. Extremely High or Hidden Interest Rates
Unlicensed moneylenders often charge excessive interest rates that are far beyond legal limits.
These may not be disclosed clearly upfront and can quickly escalate into unmanageable debt.
In contrast, licensed moneylenders must follow:
Strict caps on interest rates
Limits on late fees
Transparent pricing structures
6. Harassment, Threats, or Intimidation
One of the most dangerous aspects of dealing with unlicensed moneylenders is their method of debt collection.
They may:
- Use abusive language
- Harass borrowers or their families
- Make threats or damage property
Such actions are illegal in Singapore. Licensed moneylenders are strictly prohibited from engaging in any form of harassment.
7. They Are Not Listed on the Ministry of Law Registry
Every licensed moneylender in Singapore must be listed on the Registry of Moneylenders under the Ministry of Law.
Before taking any loan, always:
- Verify the lender’s name
- Check their licence number
- Confirm their office address
If the lender is not listed, do not proceed.
What You Should Do If You Encounter an Unlicensed Moneylender
If you suspect that you are dealing with an illegal lender:
- Do not engage further
- Do not provide personal information
- Keep records of messages or communication
- Report the matter to the authorities
Taking early action can prevent further complications.
Final Thoughts
Unlicensed moneylenders often appear convincing, especially when financial needs are urgent. However, recognising the warning signs can protect you from serious financial and personal risks.
Always choose a licensed moneylender in Singapore that operates transparently and within the law. Established providers such as Sands Credit focus on regulated practices, clear communication, and responsible lending — ensuring borrowers can make informed decisions with confidence.
Staying informed is your first line of defence.
📌 Frequently Asked Questions
Q: How can I tell if a moneylender is unlicensed in Singapore?
A: Common signs include unsolicited SMS or WhatsApp messages, no physical office, requests for upfront fees, lack of proper contracts, and refusal to provide licence details. Always verify the lender on the Ministry of Law’s Registry of Moneylenders.
Q: Are licensed moneylenders allowed to advertise through SMS or WhatsApp?
A: No. Licensed moneylenders in Singapore are not allowed to send unsolicited advertisements via SMS, WhatsApp, or cold calls. Such messages are usually from unlicensed moneylenders.
Q: What should I do if I receive a loan offer from an unknown number?
A: Do not respond or engage. Avoid sharing personal information and block the number. If necessary, report the message to the authorities.
Q: Is it illegal to borrow from an unlicensed moneylender?
A: While borrowers are generally treated as victims, dealing with unlicensed moneylenders can expose you to serious risks such as harassment, threats, and extremely high interest charges.
Q: Can unlicensed moneylenders harass me or my family?
A: Yes, and this is one of the biggest dangers. Unlicensed moneylenders often use illegal tactics such as harassment, intimidation, or contacting family members. These actions are criminal offences in Singapore.
Q: How can I check if a moneylender is licensed?
A: You can verify a lender by checking the Registry of Moneylenders on the Ministry of Law website. Always confirm the lender’s name, licence number, and office address before proceeding.
Q: What is the safest way to take a loan in Singapore?
A: The safest way is to borrow only from a licensed moneylender in Singapore or a regulated financial institution, ensuring all terms are clearly documented and explained.
Q: What should I do if I have already contacted an unlicensed moneylender?
A: Stop communication immediately, do not make any payments, and report the case to the police or relevant authorities. Avoid sharing further personal details.